
This guide covers Sensex option trading from the contract up: what one lot is worth, how Sensex compares with Nifty, how far it moves, how the two weekly expiries fit into one week, two rule-based weekly strategies with model numbers, the risk of running Sensex and Nifty together, a model week, margin, sizing, costs, backtesting and how to run the rules as an algo in QuantPower.
Sensex option trading at a glance
| Feature | Sensex options |
|---|---|
| Underlying | S&P BSE Sensex: 30 large companies |
| Exchange | BSE |
| Lot size | 20 units, from January 2026 |
| Value of one point | ₹20 per lot |
| Contract value | About ₹16 lakh with the index at 80,000 |
| Expiry | Weekly on Thursday; monthly on the last Thursday; the previous trading day if Thursday is a holiday |
| Trading hours | 9:15 am to 3:40 pm |
| Settlement | European, cash-settled at the index's official close, set by the closing auction |
| Margin for sellers | SPAN plus 2% exposure margin on each short lot, and another 2% on expiry day |
| Typical move in our model | About 706 points (0.9%) a day and 1,578 points (2%) a week, at 14% IV |
| Main risks | Overlap with Nifty positions, expiry-day gamma, wider spreads on distant strikes |
Key takeaways
- Every point of premium is ₹20 a lot. With 6 days to expiry, the at-the-money call costs about ₹616 in our model, or ₹12,326 a lot, and the put about ₹531, or ₹10,617.
- A Sensex lot carries almost the same rupee risk as a Nifty lot: about ₹14,100 against ₹14,300 for a typical day's move.
- Sensex expires on Thursday and Nifty on Tuesday, so a trader can run a weekly strategy on each. That spreads the expiry days, not the risk.
- A weekly iron condor on Sensex ties up about ₹79,000 a lot, most of it exposure margin, for a credit of about ₹4,650 in our example.
- On expiry day each short lot needs an extra 2% of contract value, about ₹32,000, so a hedged iron fly needs about ₹1.42 lakh.
- The expiry day has moved twice since 2024 and the lot size doubled in January 2026, so backtests need care.
How Sensex options work
What the index holds
Sensex tracks 30 of the largest companies listed on BSE. Nifty 50 tracks 50 companies on NSE, and the largest companies in each index are largely the same, so the two indices usually move almost in step. The differences come from the 20 extra names in Nifty and from small differences in weights. For a trader, this means that most of what is true of Nifty options is true of Sensex options once the index level and lot size are allowed for.
The contract
One lot is 20 units, up from 10 since January 2026. Every point of premium or index movement is worth ₹20 a lot, and with the index at 80,000 a contract is worth ₹16 lakh. Exchanges review lot sizes periodically, so check the current figure before sizing a trade.
Sensex options are European: they can only be exercised at expiry, and they settle in cash at the index's official closing value on expiry day. Since 3 August 2026, that closing value comes from the closing auction of the index stocks, which runs from 3:15 pm to about 3:35 pm, and the options trade until 3:40 pm. Weekly contracts expire every Thursday and the monthly contract on the last Thursday of the month. The F&O expiry calendar lists the dates.
How the expiry day has moved
BSE relaunched weekly Sensex options in May 2023 with a Friday expiry. SEBI's circular of 1 October 2024 then limited each exchange to weekly expiries on one benchmark index from 20 November 2024; BSE kept Sensex, and Bankex and Sensex 50 became monthly only. From 1 January 2025 the Sensex expiry moved to Tuesday. In 2025, SEBI limited expiries to Tuesday or Thursday so that the two exchanges would not expire on the same day, and from 1 September 2025 Sensex moved to Thursday while Nifty moved to Tuesday. BSE also stopped launching new weekly index futures from 1 July 2025.
So the Sensex expiry has been on three different weekdays in under three years. Anything built on past Sensex data has to follow the contract's expiry dates, not a fixed weekday.
Liquidity
Sensex options near the money are liquid, and volume concentrates in the current week. Strikes far from the money and contracts further out can be noticeably thinner than Nifty's, with wider gaps between the bid and the ask. Use limit orders, check every leg's bid and ask before entering, and expect stop-loss exits on distant strikes to fill further from the trigger. The option chain shows the bid, the ask and the open interest at each strike.
Sensex and Nifty options compared
Model values at the same implied volatility of 14%, with Sensex at 80,000 and Nifty at 25,000:
| Sensex options | Nifty options | |
|---|---|---|
| Exchange | BSE | NSE |
| Stocks in the index | 30 | 50 |
| Lot size | 20 | 65 |
| Value of one point | ₹20 | ₹65 |
| Contract value | About ₹16 lakh | About ₹16.25 lakh |
| Weekly expiry | Thursday | Tuesday |
| Typical day's move per lot | ₹14,111 | ₹14,331 |
| At-the-money straddle, 1 day before expiry | ₹9,357 a lot | ₹9,503 a lot |
| At-the-money straddle at 1:15 pm on expiry day | ₹5,613 a lot | ₹5,701 a lot |
Per lot, the two contracts carry almost the same risk and premium. Nifty's market is deeper, so its spreads are usually tighter; Sensex's main appeal is a second weekly expiry in the week. Our guide to Nifty option trading covers the Nifty contract in detail.
How far Sensex moves
The model's one-standard-deviation move over a number of trading days is the index level × implied volatility × √(days ÷ 252). With Sensex at 80,000 and IV at 14%:
| Period | Move in points | Share of the index | Per lot |
|---|---|---|---|
| 1 trading day | 706 | 0.9% | ₹14,111 |
| 1 week (5 days) | 1,578 | 2.0% | ₹31,552 |
About a third of the time the move is bigger than this. Real moves have fatter tails than the model and cluster around events such as RBI policy, the Union Budget, results from the largest companies and major global news. Compare the IV in the market with its recent range using the implied volatility calculator, and watch India VIX, which moves with Sensex IV.
What one lot costs: strikes with 6 days left
Model values with Sensex at 80,000 on Friday, 6 days before the Thursday expiry, with IV of 14% and an interest rate of 6.5%:
| Strike | Option | Model price | Per lot | Delta |
|---|---|---|---|---|
| 78,500 | Put | ₹94.88 | ₹1,898 | −0.13 |
| 78,800 | Put | ₹142.65 | ₹2,853 | −0.18 |
| 79,500 | Put | ₹325.36 | ₹6,507 | −0.34 |
| 80,000 | Put | ₹530.86 | ₹10,617 | −0.47 |
| 80,000 | Call | ₹616.29 | ₹12,326 | 0.53 |
| 80,500 | Call | ₹390.92 | ₹7,818 | 0.39 |
| 81,300 | Call | ₹162.42 | ₹3,248 | 0.20 |
| 82,000 | Call | ₹63.92 | ₹1,278 | 0.10 |
The at-the-money call costs more than the put because the model includes interest, which puts the futures price slightly above the index. Delta is how much the option moves for a 1-point move in Sensex.
One week, two weekly expiries

A new weekly Sensex contract becomes the front expiry on Friday morning, the day after the previous one expires. The Nifty weekly expires on Tuesday, two trading days before Sensex. That timing shapes the week for anyone who trades both:
| Day | Nifty | Sensex | What it means |
|---|---|---|---|
| Friday | Front contract has 4 days left | New front contract, 6 days left | Weekly Sensex sellers enter |
| Monday | 1 day left | 3 days left | Nifty premiums are small and fast |
| Tuesday | Expiry day | 2 days left | A Nifty expiry trade and a Sensex position are open at the same time |
| Wednesday | New front contract | 1 day left | Weekly Sensex sellers exit |
| Thursday | 5 days left | Expiry day | Sensex expiry-day trades |
The overlap on Tuesday afternoon is where the two indices most often hurt the same account at once: Nifty's expiry-day gamma is at its highest while a Sensex position, two days from expiry, is still exposed to the same move.
Sensex option strategies
| Your view | Strategy | When in the week | Main risk |
|---|---|---|---|
| Range-bound for the week | Weekly iron condor | Friday 10:00 am to Wednesday 3:00 pm | A trend or a gap through a short strike |
| A quiet final session | Expiry-day iron fly | Thursday, 1:15 to 3:10 pm | A late move, when gamma is highest |
| A move in one direction | Bull call spread or bear put spread | On a signal, held one to three days | The move fails |
Strategy 1: The weekly iron condor
An iron condor strategy sells an out-of-the-money put and call and buys further-out options as wings, so the most it can lose is fixed at entry. Here is a weekly rule set for Sensex:
- Instrument: Sensex options, current weekly expiry.
- Entry: Friday at 10:00 am, if India VIX is below 20.
- Legs: sell the put and the call nearest to 0.20 delta, and buy wings 1,000 points further out. Place the wings first.
- Target: close when the position can be bought back for half the credit.
- Stops: close if the position's value reaches twice the credit, or if Sensex closes beyond a short strike.
- Time exit: Wednesday at 3:00 pm, before the expiry day.
With Sensex at 80,000, 6 days to expiry and IV at 14%:
| Leg | Strike | Model price |
|---|---|---|
| Buy put | 77,800 | ₹31.90 |
| Sell put | 78,800 | ₹142.65 |
| Sell call | 81,300 | ₹162.42 |
| Buy call | 82,300 | ₹40.79 |
| Net credit | ₹232.38, or ₹4,648 a lot |
The most the position can lose is the wing width less the credit: (1,000 − 232.38) × 20 = ₹15,352. At expiry it breaks even at 78,568 and 81,532. Margin is about ₹79,000, so the credit is about 6% of the money blocked.
If Sensex and IV stay unchanged, the position is worth ₹142.63 by Monday and ₹7.47 by Wednesday afternoon, so in a quiet week the 50% target usually closes the trade by Tuesday. The risk is the opposite week: a trend that carries Sensex through a short strike, about 1.5% away on each side, within days. The close beyond a short strike ends the trade before the loss approaches the maximum. The short strangle strategy is the same trade without wings: a larger credit, no cap on the loss and much more margin.
Strategy 2: The expiry-day iron fly
On expiry day the remaining time value is small and falls fast. An iron fly strategy sells the at-the-money call and put and buys wings, collecting most of that value with a fixed maximum loss. The rules:
- Day: Thursday expiry only, with no major event scheduled that day.
- Entry: 1:15 pm. Sell the at-the-money call and put, and buy wings 1,000 points away.
- Stop: close if the position's value reaches 1.5 times the credit.
- Time exit: 3:10 pm, before the closing auction starts at 3:15 pm.
- Frequency: one trade per expiry.
With Sensex at 80,000 at 1:15 pm and IV at 14%, the model prices are ₹142.90 for the call and ₹137.77 for the put, and the wings cost ₹0.26 and ₹0.21. The net credit is ₹280.20, or ₹5,604 a lot. The most the position can lose is (1,000 − 280.20) × 20 = ₹14,396, and it breaks even at 79,720 and 80,280.
Each short leg needs 2% exposure margin plus the extra 2% for expiry day, ₹64,000 a lot, so the two short legs need ₹1.28 lakh on top of the ₹14,396 maximum loss: about ₹1.42 lakh in total.
Outcomes at 3:10 pm in the model:
| Sensex at 3:10 pm | Position value | P&L per lot, before charges |
|---|---|---|
| Unchanged at 80,000 | ₹108.02 | +₹3,444 |
| 130 points higher | ₹154.88 | +₹2,506 |
| 260 points higher | ₹263.58 | +₹332 |
| 480 points higher, with no stop | ₹480.77 | −₹4,011 |
The stop at ₹420.30 limits the loss to about ₹2,802 before slippage, and it is reached if Sensex is about 405 points from the strike by 2:15 pm. The same trade on Nifty on Tuesday collects about ₹5,687 a lot at the same IV, for almost the same margin. Our guide to hero zero option trading on Nifty and Sensex covers the expiry session in full: buying and selling strategies, the Greeks hour by hour, and the closing auction.
Strategy 3: Directional spreads
Debit spreads take a view on direction with a known maximum loss. A bull call spread buys a call and sells a higher one; a bear put spread buys a put and sells a lower one. Automated versions usually enter on a signal from the Sensex futures or the index itself, such as an opening range breakout or a close above a moving average, and exit at a target, a stop or a time limit. Because weekly options decay fast, directional trades on Sensex tend to use the next week's contract once the current one has fewer than three days left.
Running Sensex and Nifty together
Many traders run weekly strategies on both indices, one expiring on Tuesday and one on Thursday. It can make good use of capital and time, but it does not spread the risk.
Here is what a sharp move does on a Tuesday afternoon. Suppose a Nifty expiry-day iron fly is open from 1:15 pm, and the Sensex weekly condor from Friday is still running with two days left. If the market rallies 1% by 2:15 pm, the Nifty fly, without its stop, would be down about ₹9,705 a lot, and the Sensex condor would lose about ₹2,788 a lot in the same hour. The stop on the fly caps its loss near ₹2,844, but both positions lose at once, and the account's daily limit has to allow for both.
A few rules help:
- Add up the Greeks across both indices, especially delta and gamma, and treat the total as one position. A delta neutral strategy shows how to keep the combined delta near zero.
- Set an account-level limit with an MTM stop loss, so that one bad day on both indices cannot exceed it.
- Stagger rather than duplicate. Use different structures or different days rather than the same trade on both indices; for example, skip the Nifty expiry trade on Tuesdays when the Sensex condor is close to a short strike.
- Count Bank Nifty and FinNifty too. Financial stocks carry large weights in both Sensex and Nifty, so positions on Bank Nifty or FinNifty option trading add to the same exposure.
A model week on one lot
Here is one week with the two selling strategies, one lot each. Prices come from the model as Sensex and IV change; it shows the mechanics, not a record of results.
| Day | Sensex | IV | What happens | Model price | P&L before charges |
|---|---|---|---|---|---|
| Fri, 10:00 am | 80,000 | 14% | Sell the 77,800 / 78,800 / 81,300 / 82,300 iron condor | Credit ₹232.38 | |
| Mon | 80,300 | 13.5% | Hold; the condor is worth ₹143.51 | +₹1,777 open | |
| Tue | 80,150 | 13.8% | The condor reaches its target | Bought back at ₹116.19 | +₹2,324 |
| Thu, 1:15 pm | 80,380 | 13% | Sell the 80,400 iron fly with 79,400 / 81,400 wings | Credit ₹261.92 | |
| Thu, 2:20 pm | 80,780 | 13% | Sensex rallies 400 points and the stop fires | Bought back at ₹395.88 | −₹2,679 |
The week lost ₹355 before charges. Charges came to about ₹402 (₹200 on the condor and ₹202 on the fly), so the net loss was about ₹757.
Two things stand out. The condor did its job: a quiet start to the week, IV drifting lower and the target reached on Tuesday. The fly met the late rally that expiry-day sellers are paid to accept, and the stop kept the loss to about half the credit plus slippage. A week like this is normal for a selling strategy; the rules only make sense measured over many weeks.
Margin for Sensex option sellers
Buyers pay the premium in full and post no margin. Sellers post two amounts:
- SPAN margin covers the worst one-day loss across the clearing corporation's price and volatility scenarios. It changes every day with volatility.
- Exposure margin, also called extreme loss margin, is 2% of the contract value on each short lot: about ₹32,000 at 80,000, using the previous day's close.
On expiry day, short index options expiring that day carry another 2% of contract value, or ₹32,000 more per short lot. It applies to positions carried into the day and to new ones sold during the day. For a fully hedged position, SPAN falls to roughly the most the position can lose, so the exposure margin becomes the larger part. Approximate figures per lot with Sensex at 80,000:
| Position | What the margin is made of | Approximate margin |
|---|---|---|
| Naked short straddle | SPAN plus ₹64,000 exposure margin | ₹1.5 to 1.8 lakh, similar to Nifty (our estimate) |
| Weekly iron condor, 1,000-point wings | Maximum loss of ₹15,352 plus ₹64,000 | About ₹79,000 |
| Iron fly on expiry day, 1,000-point wings | Maximum loss of ₹14,396 plus ₹1,28,000 | About ₹1.42 lakh |
| Bought call or put | The premium only | The premium |
Margin is what the broker blocks, not what you can lose. Check the live figure in your broker's calculator before each trade.
Sizing a Sensex position
Size from the loss you are prepared to take on one trade. Take an account of ₹10 lakh with a limit of 1% (₹10,000) per trade and 2% (₹20,000) per day:
| Strategy | Loss at the stop, with charges and slippage | Lots | Margin | Worst case |
|---|---|---|---|---|
| Weekly iron condor | About ₹5,200 a lot | 1 | About ₹79,000 | ₹15,352, the maximum loss |
| Expiry-day iron fly | About ₹3,300 a lot | 2 | About ₹2.85 lakh | ₹28,792 for two lots |
Two condor lots would risk about ₹10,400 at the stop, just above the limit, so this account trades one. Three iron flies would fit the per-trade limit but block over 40% of the account for one afternoon; two block about 28%. If the same account also runs a Nifty strategy, the daily limit of ₹20,000 has to cover both on a Tuesday.
Costs per round trip
Each order pays brokerage (₹20 here), exchange transaction charges, the SEBI fee and GST; each sale pays STT at 0.15% of the premium; each purchase pays stamp duty.
| Trade, one lot | Orders | Charges | Share of the credit |
|---|---|---|---|
| Weekly iron condor | 8 | About ₹205 | 4.4% of ₹4,648 |
| Expiry-day iron fly | 8 | About ₹200 | 3.6% of ₹5,604 |
On four-leg trades, brokerage is most of the cost: ₹160 of about ₹200. The weekly condor's credit per lot is small, so its costs take a larger share than on a monthly trade; trading more lots per order spreads the brokerage. Use the brokerage calculator for your broker's rates.
Backtesting a Sensex strategy
- Follow the expiry dates, not a weekday. Sensex weeklies expired on Friday until December 2024, on Tuesday from January to August 2025 and on Thursday since September 2025.
- Use the right lot size. The lot was 10 units until the change to 20 in January 2026. Test in rupees per unit, or apply the lot size in force on each date.
- Allow for growing liquidity. Sensex options have traded far more since the 2023 relaunch, so early data can show wider spreads than today's market, and today's spreads are still wider than Nifty's on distant strikes.
- Model the settlement correctly. Since 3 August 2026 the closing auction sets the settlement price and options trade until 3:40 pm.
- Test both indices together if you plan to run both, so the backtest shows the combined drawdown on days when both lose.
- Tag the event weeks and compare the results with the rest.
Our guides on how to backtest trading strategies and avoiding overfitting cover the method, and the backtesting engine runs the tests with costs and slippage.
Setting up a Sensex algo strategy in QuantPower
Each rule maps to a setting. Using the weekly iron condor as the example:
| Rule | Example setting |
|---|---|
| Instrument | Sensex options, current weekly expiry |
| Entry | Friday, 10:00 am |
| Filter | India VIX below 20 |
| Legs | Sell the 0.20-delta put and call; buy wings 1,000 points further out |
| Order sequence | Wings first, then the short legs |
| Target | 50% of the entry credit |
| Stop | Twice the entry credit, or a Sensex close beyond a short strike |
| Time exit | Wednesday, 3:00 pm |
| Account limit | Daily MTM loss limit covering all strategies |
Step 1. Build the structure
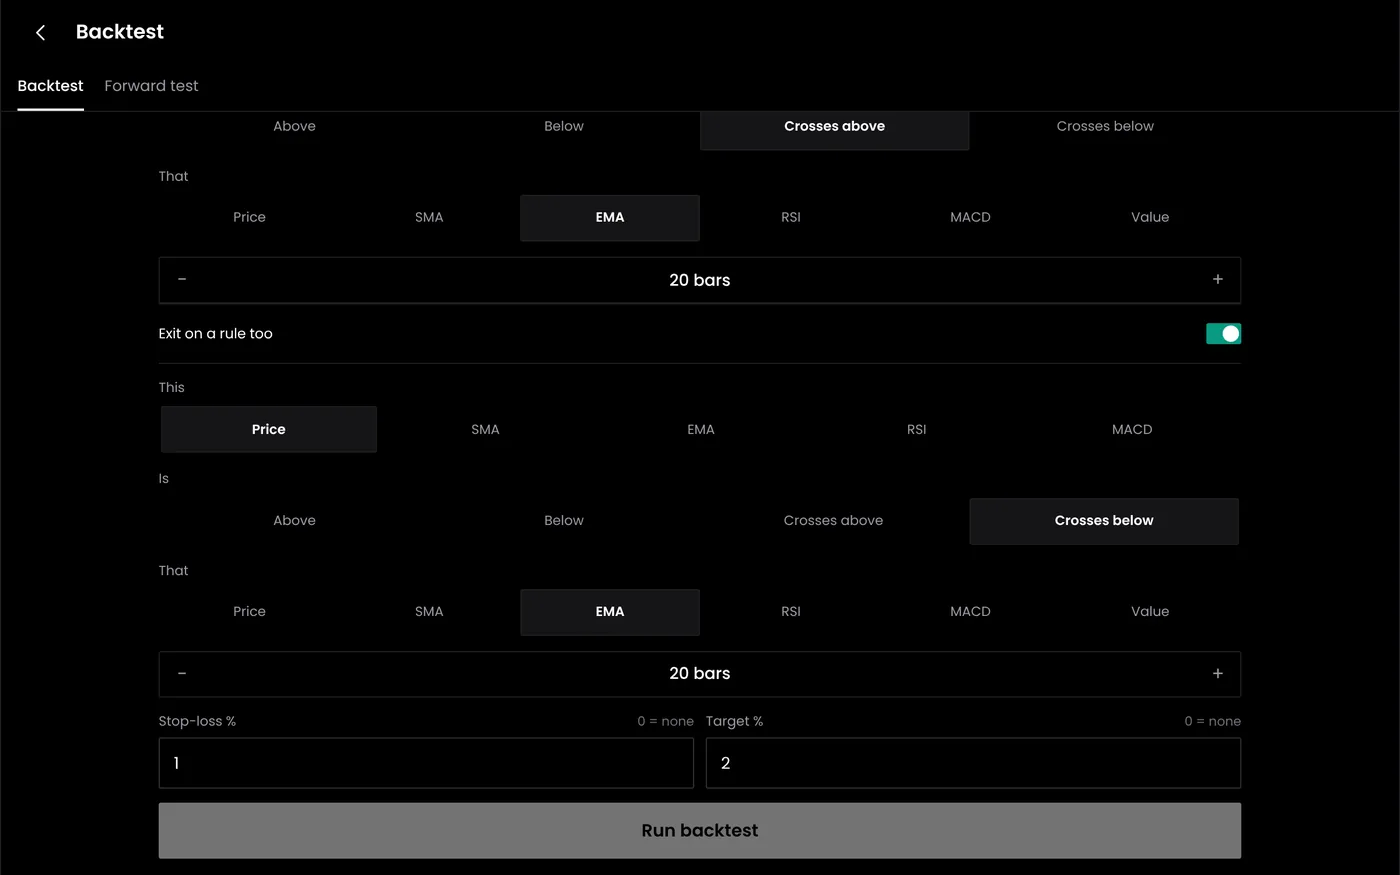
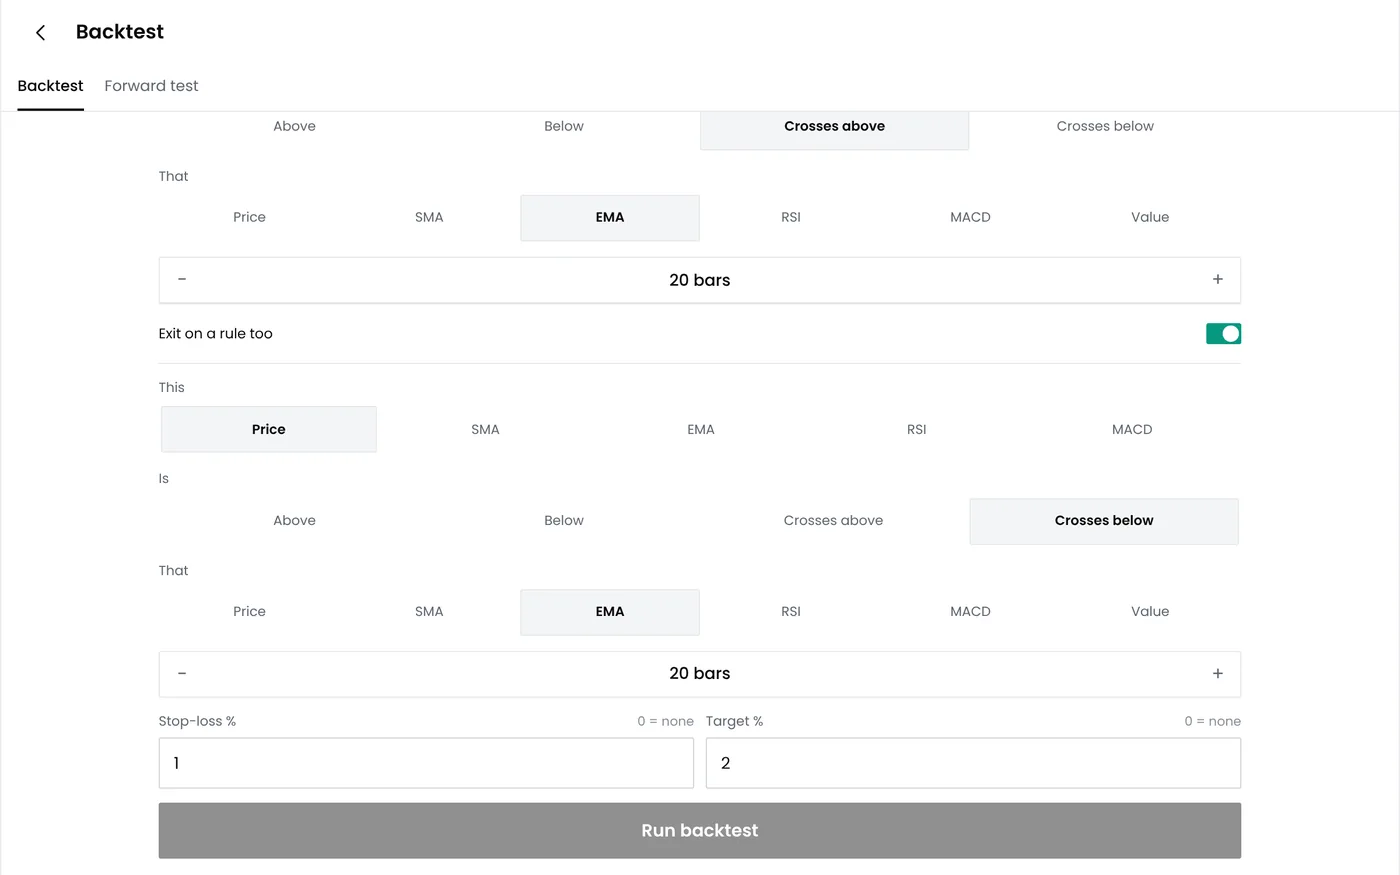
In the strategy builder, choose Sensex weekly options and add the four legs, with the short strikes chosen by delta and the wings set 1,000 points away. The builder shows the payoff, the credit and the Greeks before you save.
Step 2. Set the entry, exits and filters
Add the Friday entry, the VIX filter, the 50% target, both stops and the Wednesday exit. For the expiry-day iron fly, set the strategy to run on Thursdays only, from 1:15 pm, with the 3:10 pm exit.
Step 3. Backtest it
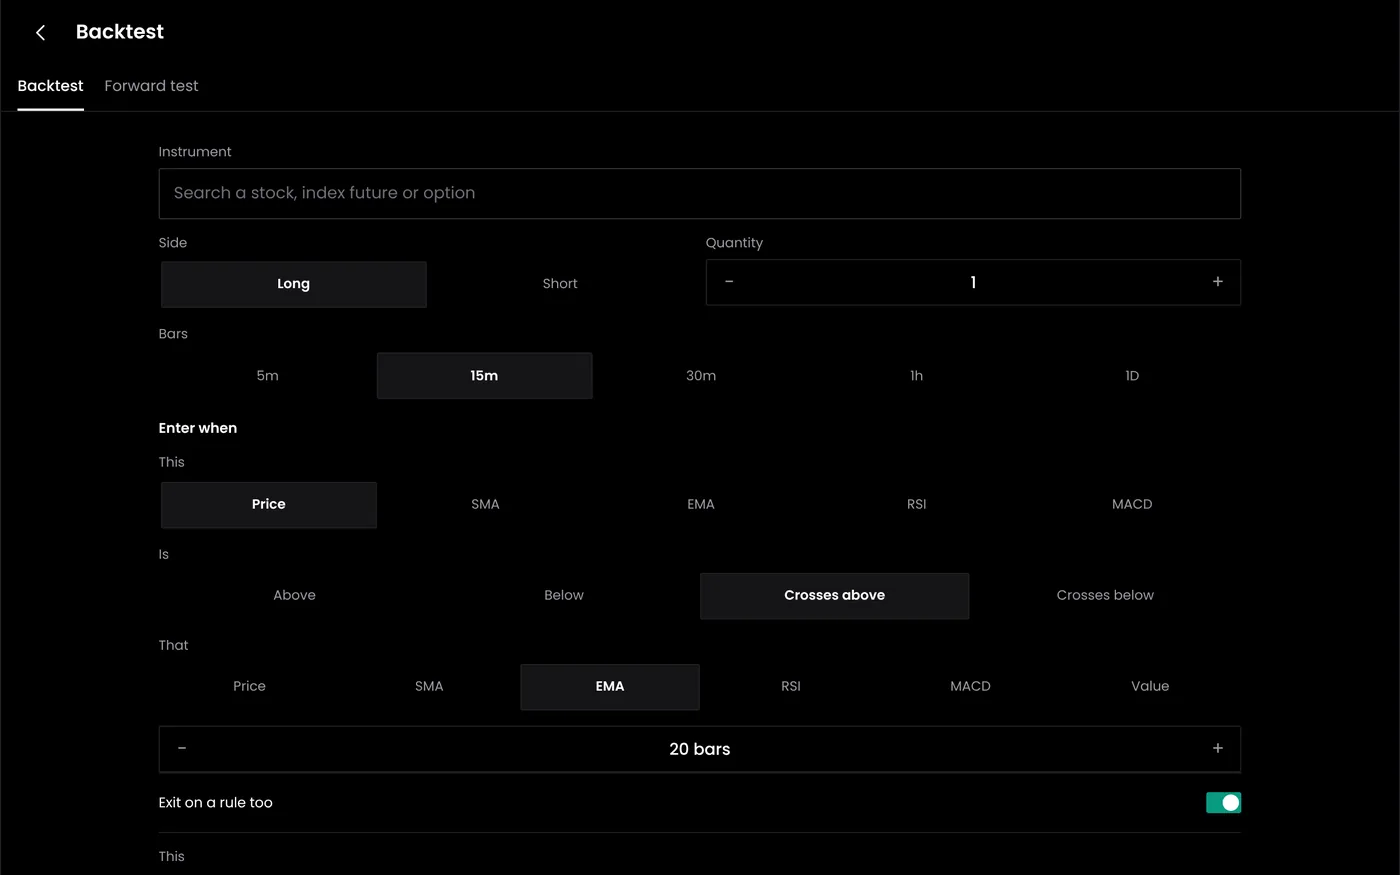
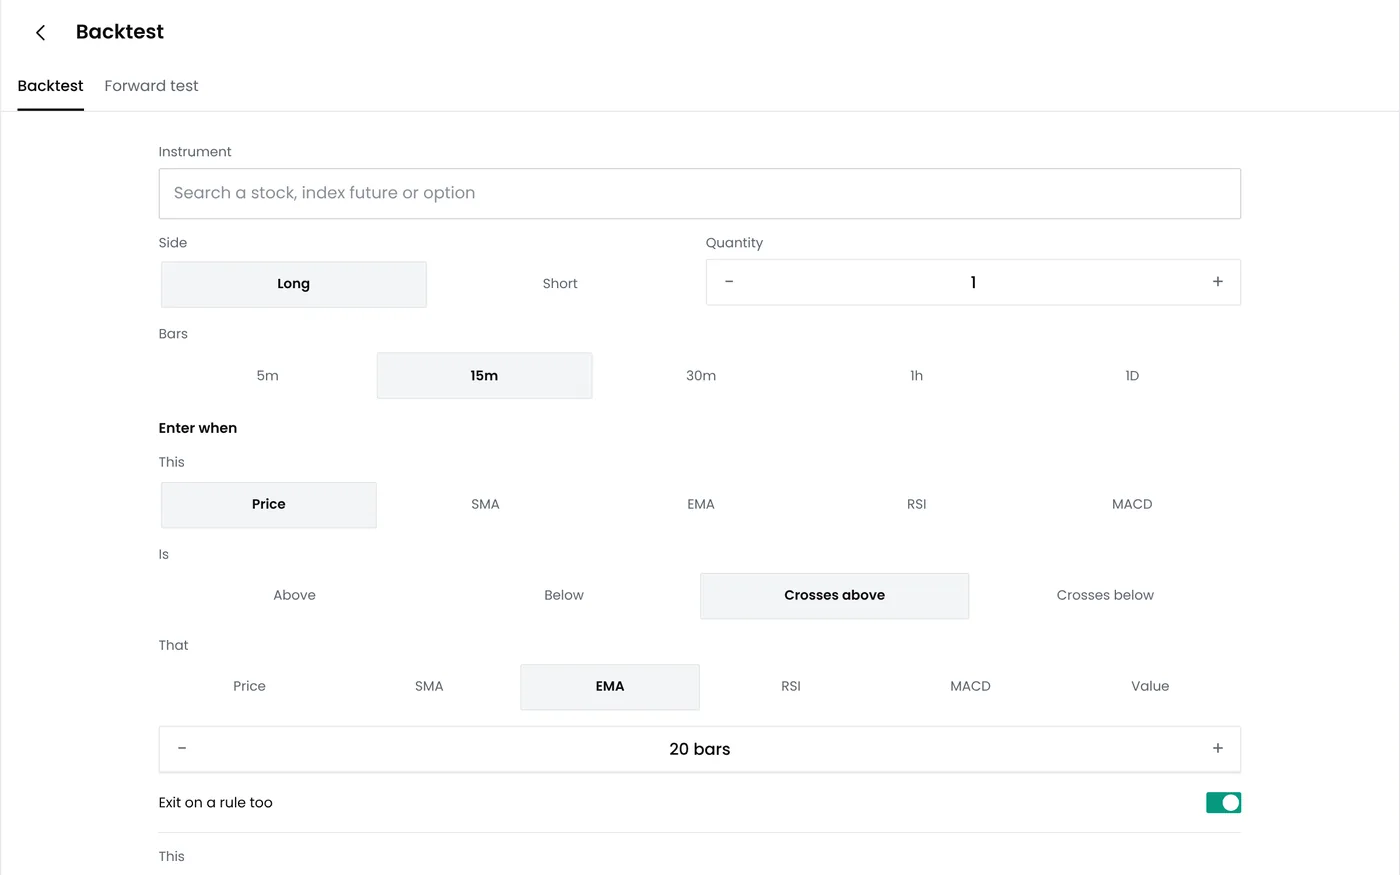
Run the rules over past weekly expiries with charges and slippage on, following the expiry dates of each period. Change one setting at a time, such as the delta, the wing width or the target, and see how many trades each change affects.
Step 4. Paper trade it
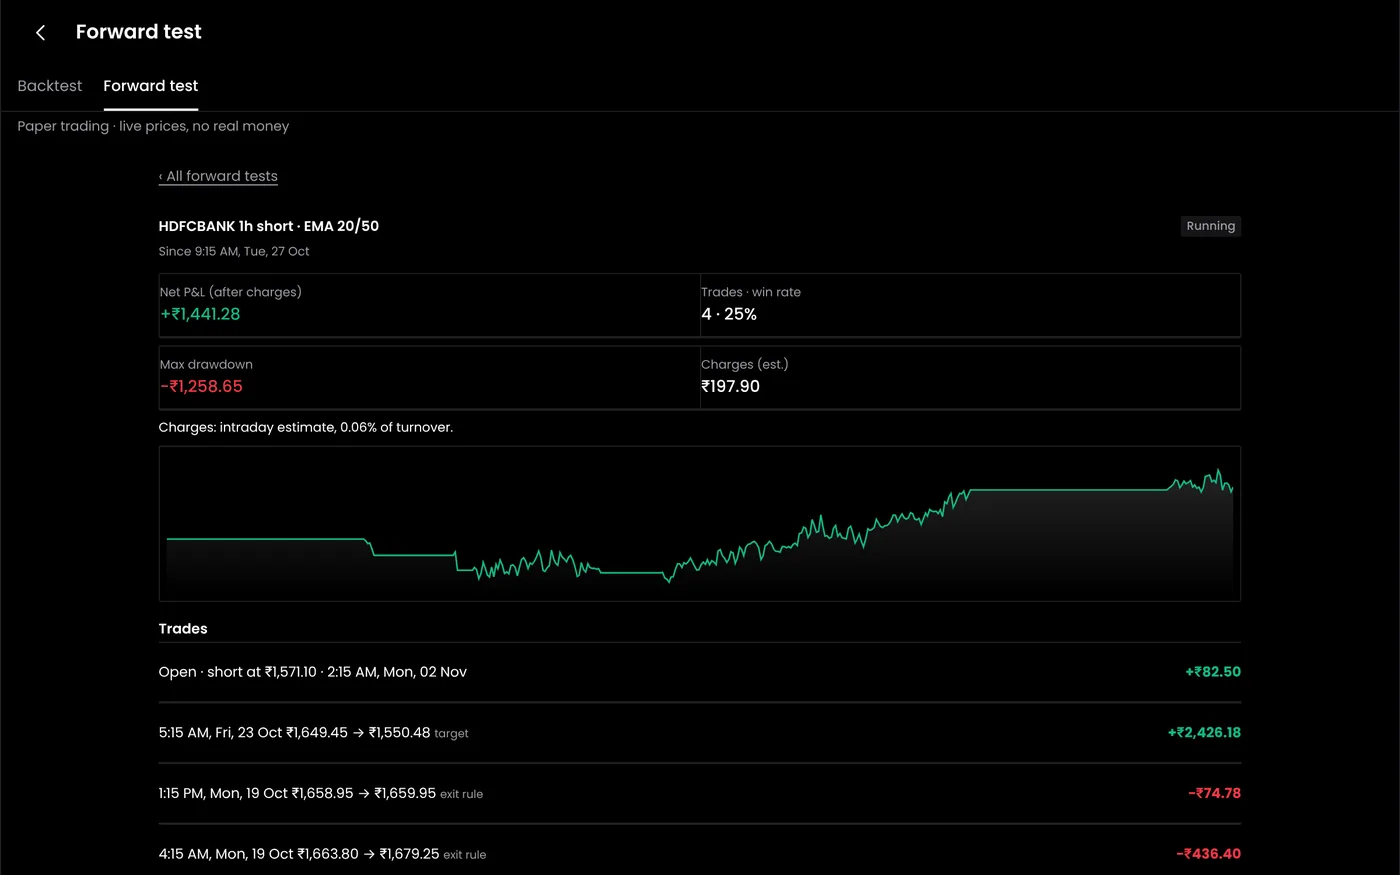
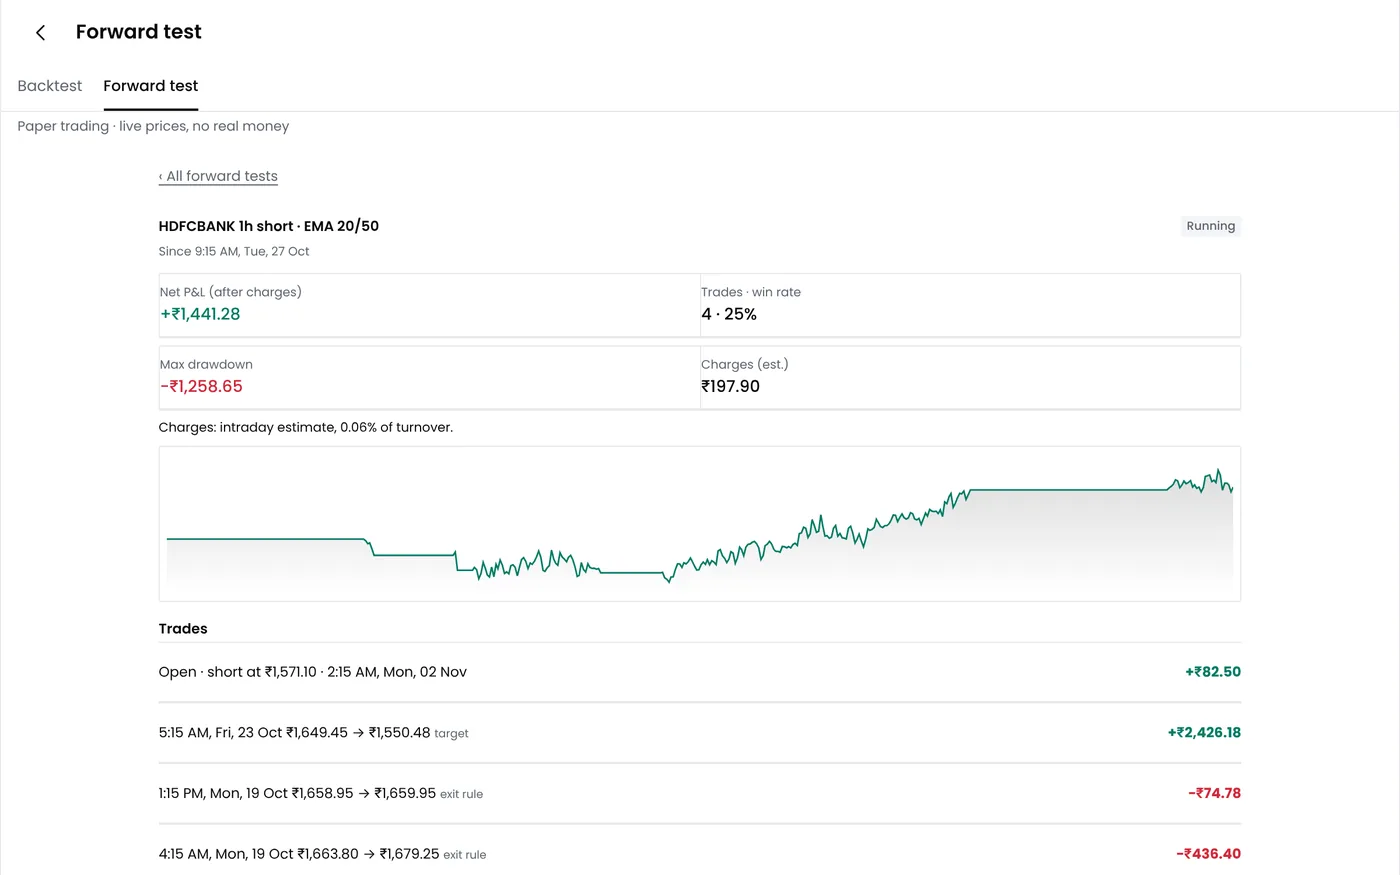
Run the strategy on live prices with virtual money for several weeks, alongside any Nifty strategy you plan to run. Compare each fill with the price the backtest assumed.
Step 5. Set the account limit
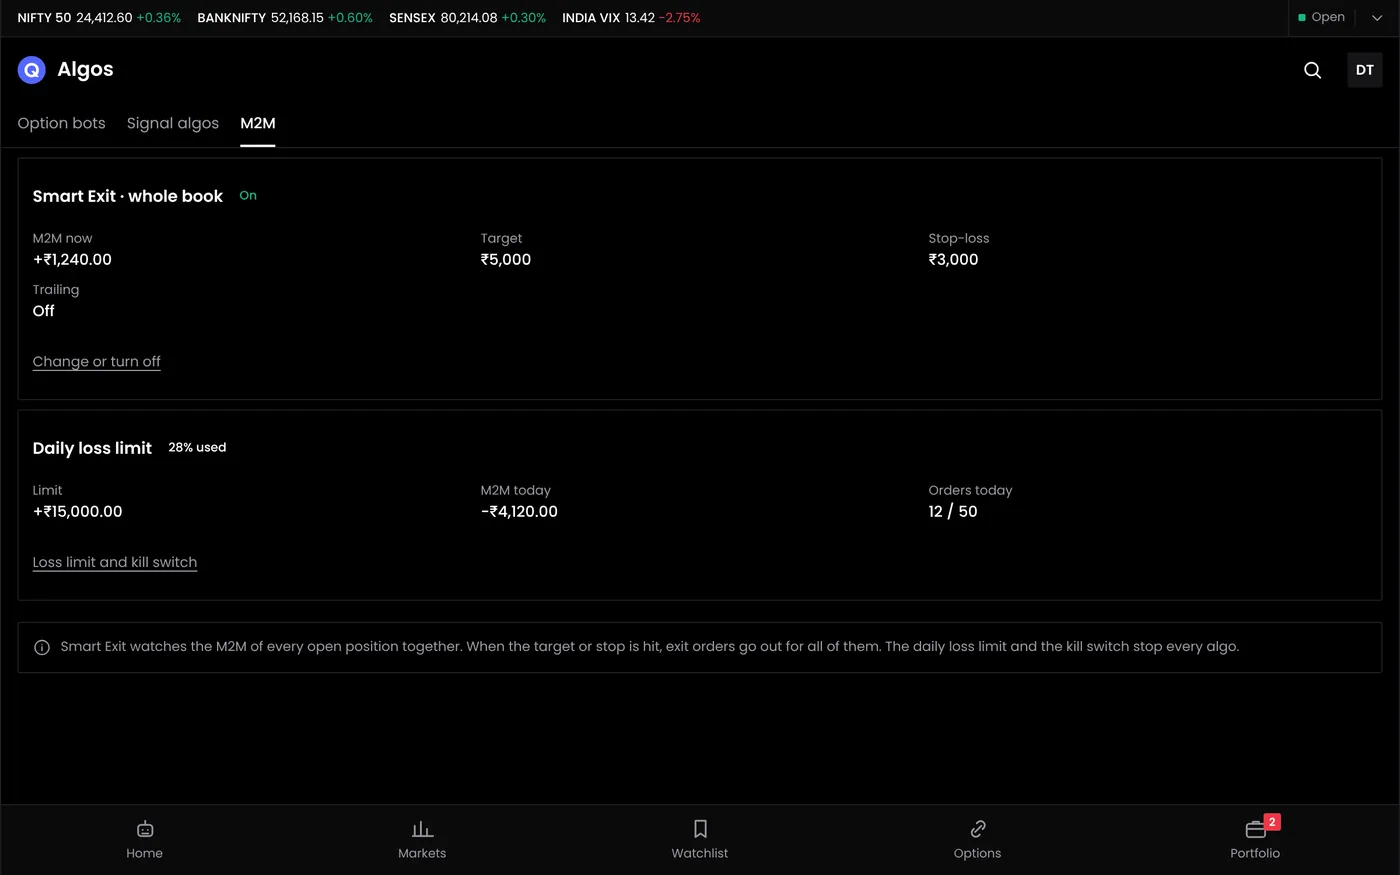
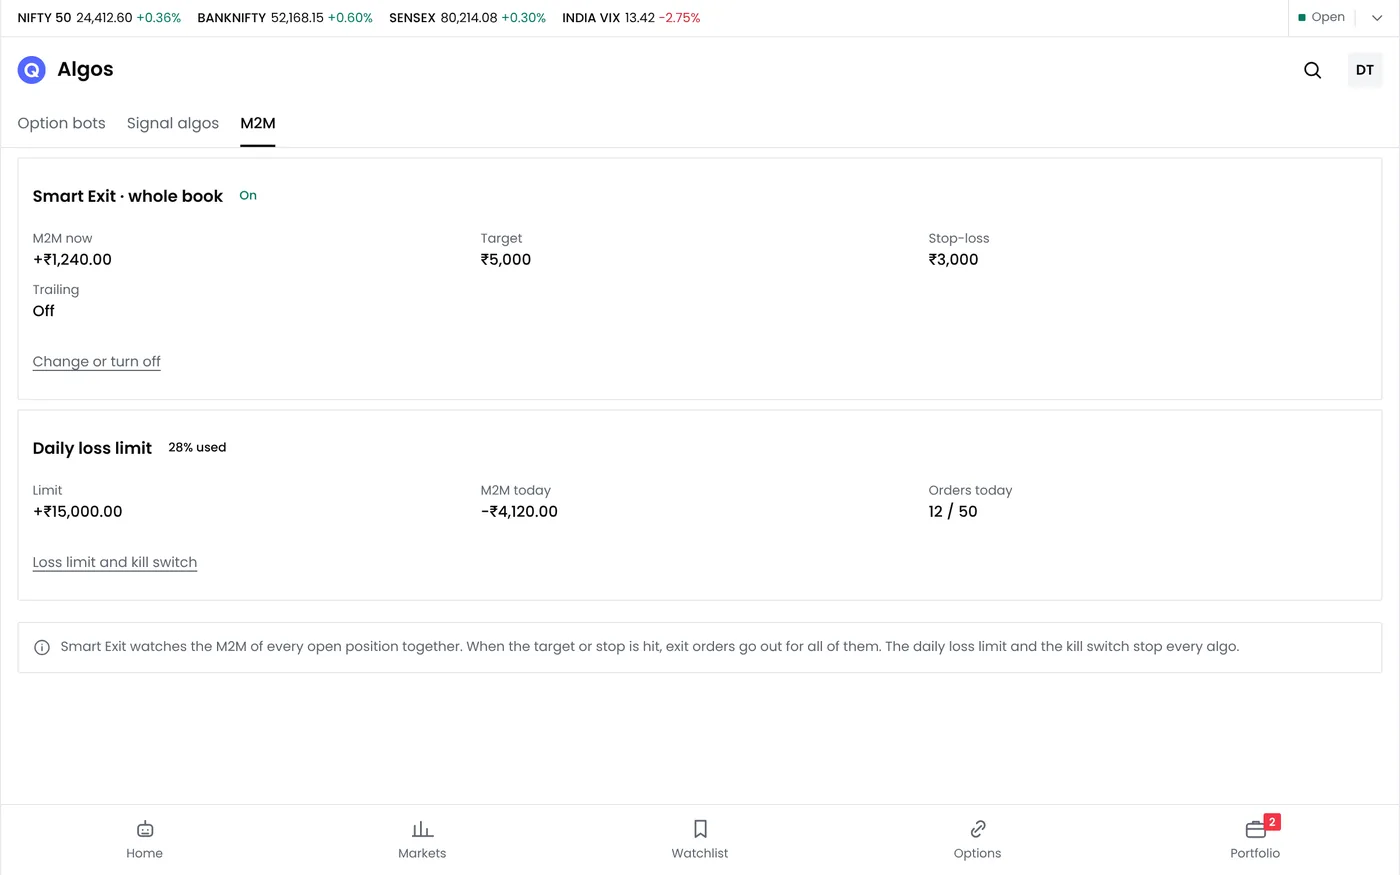
Set the daily MTM loss limit in the risk settings before going live. It closes every position when it is hit, including those from other strategies, which is what protects an account running both Sensex and Nifty.
Step 6. Deploy and monitor
Connect your broker, choose the strategy and the number of lots, confirm the limits and deploy. The bot places the wings before the short legs and watches the target, the stops and the time exit. A market alert can flag event days, and if your signals come from TradingView charts, signal trading turns the alerts into orders. Orders go through your connected broker under the requirements applicable to your strategy and account; a named example is not a claim of strategy approval.
Measuring a Sensex strategy
| Measure | What to look for |
|---|---|
| Net profit after charges | Positive across most rolling three-month periods, not just in total |
| Average win and average loss | For sellers, one average loss should not wipe out several weeks of wins |
| Return on margin | Profit as a share of the margin blocked, week by week |
| Maximum drawdown | In rupees and in weeks, and for Sensex and Nifty strategies combined |
| Event weeks against quiet weeks | Whether the strategy depends on calm weeks only |
| Slippage against the model | Fills on stops and on distant strikes compared with the backtest |
A trade journal helps track these week by week.
Common Sensex option trading mistakes
- Running the same trade on Sensex and Nifty and treating it as two separate risks.
- Forgetting the Tuesday overlap, when a Nifty expiry trade and a Sensex weekly position are open together.
- Sizing with the old lot size of 10, which doubles the real position.
- Selling distant strikes with market orders and exiting through wide spreads.
- Holding past 3:15 pm on expiry day into the closing auction without meaning to.
- Testing on a fixed weekday when the expiry day has changed twice.
Pre-trade checklist
- You know the current lot size (20) and the expiry date of the contract.
- The event calendar for the week is checked.
- India VIX and the option's IV are within the range your rules allow.
- Margin is available, including the extra 2% if you will hold short options on expiry day.
- The bid and ask of every leg are close enough to trade.
- The target, stops and time exit are set, along with the account's daily loss limit.
- Any open Nifty, Bank Nifty or FinNifty positions are counted in the same limits.
Start your free trial
Connect your broker, build a strategy and test it on paper before a single live order goes out.
Frequently asked questions
How do I start Sensex option trading?
Activate the F&O segment with your broker and check that BSE derivatives are enabled. Learn the contract (20 units, weekly expiry on Thursday), start with defined-risk trades such as spreads or an iron condor, and paper trade the rules for several weeks before using real money.
Does Sensex have weekly options?
Yes. Since November 2024, Sensex has been the only BSE index with weekly options. They expire every Thursday.
What is the Sensex lot size?
20 units since January 2026; it was 10 before. Each point is worth ₹20 a lot, so a contract at 80,000 is worth ₹16 lakh.
When does Sensex expire?
Weekly contracts expire every Thursday and the monthly contract on the last Thursday of the month, or on the previous trading day if Thursday is a holiday. The settlement price is the index's official close, set by the closing auction from 3:15 pm.
Is Sensex option trading similar to Nifty option trading?
Very similar. The two indices move closely together and carry almost the same rupee risk per lot, so the same strategies apply. The lot size, expiry day, liquidity and charges differ.
Can I run the same strategy on Nifty and Sensex?
You can, but your risk roughly doubles, because a large move hits both. Treat them as one combined position, with one account-level loss limit.
How much margin do I need to sell Sensex options?
Each short lot carries exposure margin of 2% of the contract value, about ₹32,000 at 80,000, plus SPAN. A weekly iron condor with 1,000-point wings needs about ₹79,000 a lot, and a naked short straddle roughly ₹1.5 to 1.8 lakh in our estimate. On expiry day each short lot needs another ₹32,000.
Can I automate Sensex option trading?
Yes. Your rules run through your own broker account on broker infrastructure or the client’s own static IP setup. Client-hosted operation needs its host and session available; broker-hosted clients do not need their own static IP. Ready-made strategy templates, such as straddles and iron flies, load into the strategy builder; you edit and run them as your own strategy.
Related guides and terms
- Nifty option trading, FinNifty option trading and Bank Nifty
- Hero zero option trading and the Nifty expiry date
- Iron condor strategy, iron fly strategy, short strangle strategy and short straddle strategy
- Bull call spread, bear put spread and option buying strategies
- Option greeks, theta meaning and gamma meaning
- F&O margin calculator, hedge margin benefit and brokerage calculator
Sources
- BSE: Equity derivatives contract specifications for Sensex options, bseindia.com (lot size, expiry, settlement)
- BSE circular of 28 November 2024: revised expiry days for Sensex, Bankex and Sensex 50 derivatives from 1 January 2025
- SEBI circular SEBI/HO/MRD/TPD-1/P/CIR/2024/132: Measures to strengthen the equity index derivatives framework, 1 Oct 2024 (one weekly benchmark per exchange and an additional 2% extreme loss margin on expiry day, from 20 November 2024)
- SEBI circular of 26 May 2025 limiting equity derivatives expiries to Tuesday or Thursday, and the exchanges' June 2025 notices moving Sensex to Thursday and Nifty to Tuesday from 1 September 2025
- NSE circular of 30 May 2026: equity derivatives trading until 3:40 pm from 3 August 2026, alongside the closing auction session in the cash market
- SEBI, Profitability of Individual Traders in the Equity Derivatives Segment (FY25–FY26), PR No. 50/2026, 20 August 2026